AUGUST 13, 2026
FHFA review
FHFA Director William Pulte publicly responded to a post raising Fannie Mae and Freddie Mac treatment of Sharia-compliant home financing: “We are looking into this right now.”
How a Sharia-compliant financial product was engineered into America’s federal housing system — and why federal officials are looking at it now.
Islamic law did not replace American mortgage law. A privately designed financial product whose defining constraints came from Islamic jurisprudence was translated into American mortgage instruments and connected to the federally supported secondary housing market.
The arrangement is more than two decades old. What changed in 2026 is political attention.
FHFA Director William Pulte publicly responded to a post raising Fannie Mae and Freddie Mac treatment of Sharia-compliant home financing: “We are looking into this right now.”
As of August 25, 2026, no public FHFA order has been identified terminating or suspending Sharia-compliant financing arrangements. Pulte has instead publicly described the programs as being made available and marketed more broadly.
The current review concerns a structure that was engineered, regulated and integrated into the U.S. mortgage market years before it became a national political issue.
FHFA Director William Pulte has since publicly reframed the issue around access rather than removal, stating that Sharia-compliant mortgage programs would be “open AND marketed to ALL AMERICANS.” The significance is not that the underlying structure disappeared. It is that a financing model designed to comply with Islamic law is being positioned as a mainstream mortgage option available beyond Muslim buyers. View Pulte’s August 20, 2026 statement.
Pulte’s August 13, 2026 post is the clearest current public signal that federal officials are examining the arrangement.
Freddie Mac’s own securities documentation expressly contemplates financing arrangements designed to comply with Islamic law.
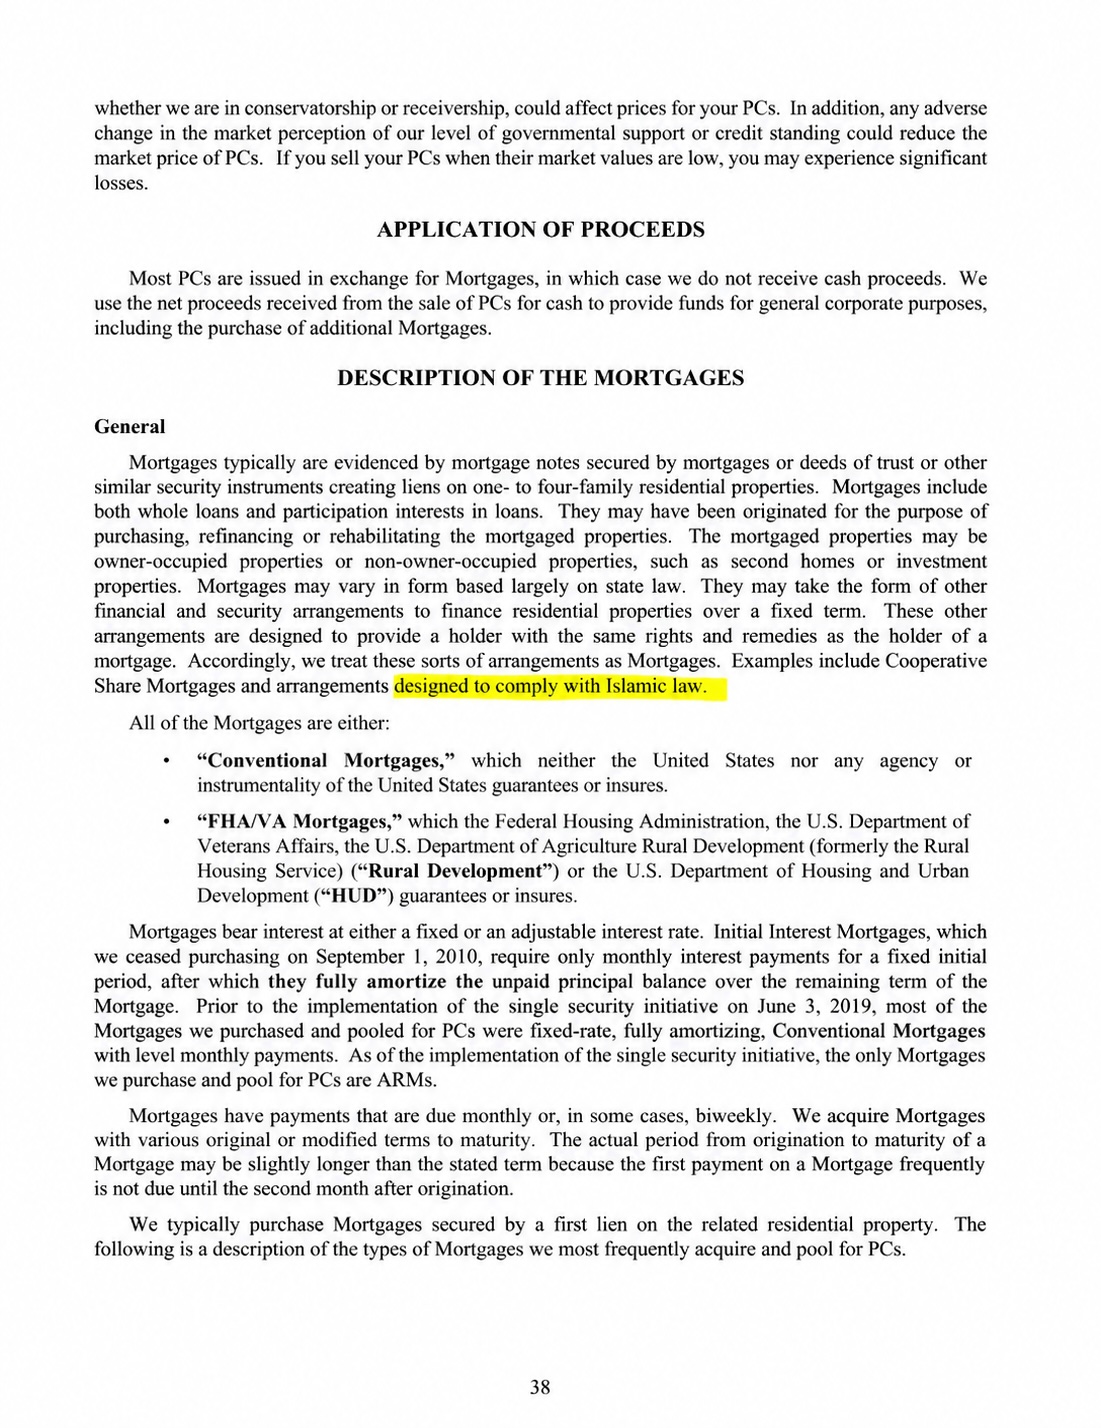
Freddie Mac recognizes arrangements that may take forms other than ordinary mortgage notes while still being treated as mortgages within its system — including arrangements “designed to comply with Islamic law.”
Guidance Residential says its model emerged from a multi-year design process involving American lawyers and Islamic-finance scholars.
The model is organized as declining co-ownership rather than being described by the provider as an ordinary interest-bearing loan.
Guidance says the structure was developed through a three-year research process involving 18 law firms and Islamic-finance scholars .
Guidance says the program has provided more than $10 billion in financing to more than 40,000 families .
The religious requirements were not added as marketing after the fact. They were part of the product’s design constraints from the beginning.
A 2003 U.S. patent application for the declining-balance co-ownership structure identifies three inventors and makes secondary-market compatibility part of the architecture.
Guidance Financial Group
Business and product architect named on the 2003 co-ownership patent application.
Co-inventor
Named alongside Hammour and Milano on the filing that formalized the declining-balance co-ownership structure.
Legal / regulatory structuring
Named co-inventor; later professional biographies also describe his work on Sharia-compliant co-ownership financing.
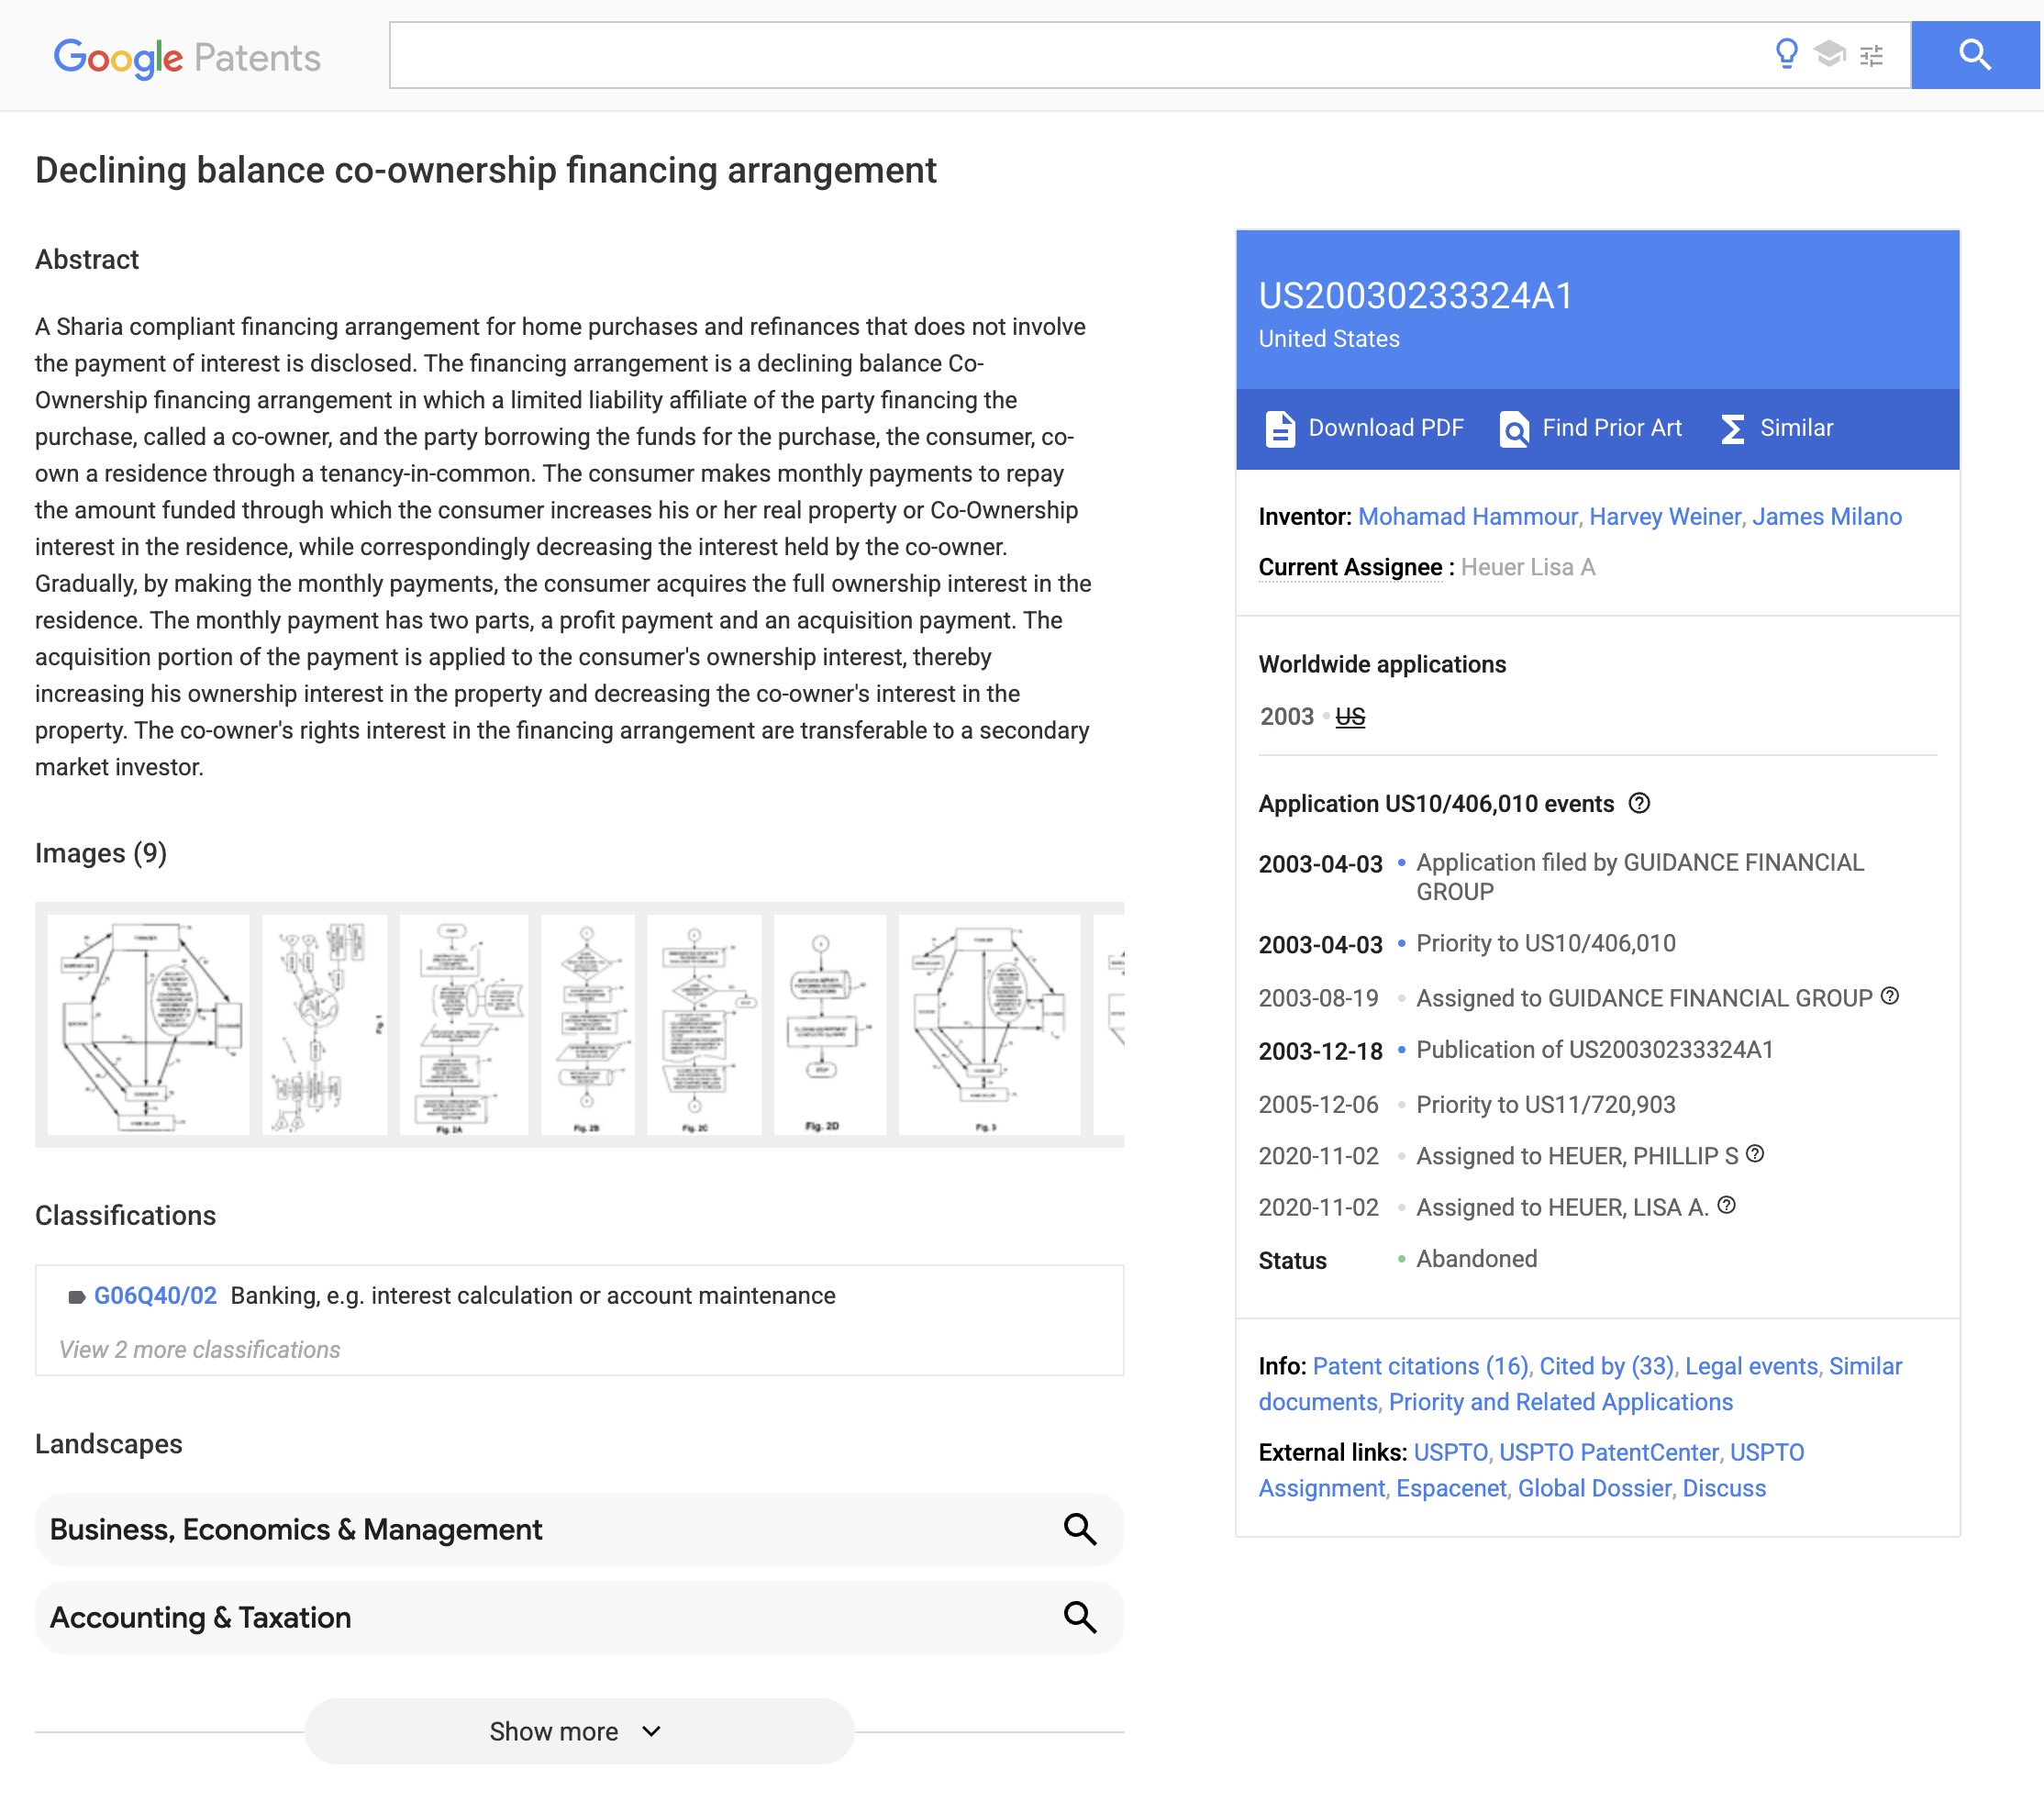
The filing explicitly contemplates a secondary-market investor such as Freddie Mac, Fannie Mae, or an investment banker.
A 2005 Massachusetts Department of Revenue ruling explains the payment mechanics in unusually direct language.
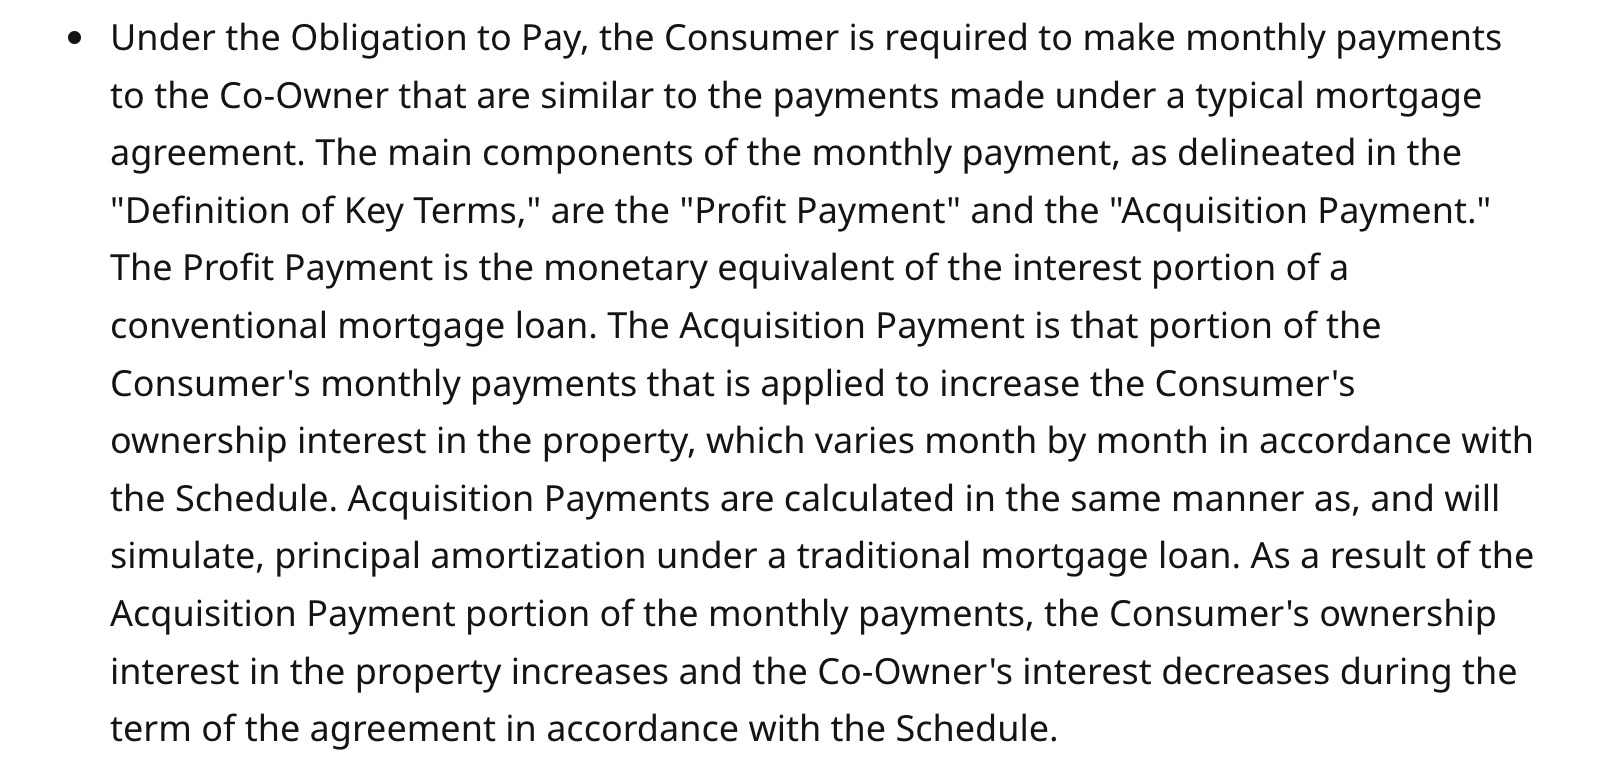
The ruling calls the Profit Payment the monetary equivalent of the interest portion of a conventional mortgage loan .
The Acquisition Payment increases the consumer’s ownership share and is calculated to simulate principal amortization .
The same ruling says Freddie treats the arrangement “in a manner similar to other mortgage transactions in its system.”
Residential Capital bankruptcy records preserve an unusually explicit contractual breadcrumb.
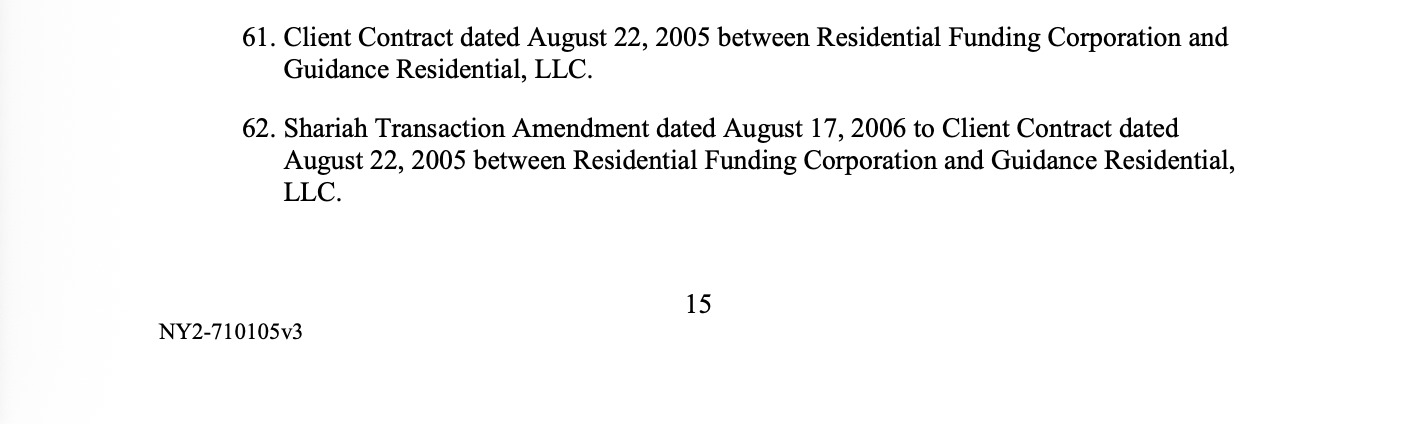
The schedule lists a Guidance Residential Client Contract dated August 22, 2005 followed by a “Shariah Transaction Amendment” dated August 17, 2006.
The public schedule proves the amendment existed. It does not reveal the amendment’s full substantive provisions. We cannot say exactly which clauses it changed without the underlying agreement.
The religious characterization changed. The surrounding American legal and mortgage machinery did not disappear.
co-ownership
profit payment
acquisition payment
Musharakah
no riba
co-ownership agreement
obligation to pay
security instrument
assignment
contract amendment
underwriting
servicing
secondary market
foreclosure
securitization
Federal context: a 2005 Federal Reserve Bank of New York speech discussed Fannie Mae and Freddie Mac participation in Sharia-compliant home finance inside existing American regulatory structures.
The largest demonstrated system-level advantage is not a special consumer subsidy. It is liquidity and scale: a specialized religious-finance product gains access to the deep U.S. secondary mortgage market.
A privately designed financial product whose governing constraints came from Islamic jurisprudence was translated into American mortgage instruments and given access to federally supported secondary-market infrastructure.
The documents do not show that America adopted Sharia law. They show that American financial institutions engineered a legal and market interface capable of accommodating a Sharia-designed product.
The question is no longer whether the system exists. The documents show that it does. The emerging federal position appears to be broader availability rather than removal — but the scope and implementation of that policy remain worth watching.
This dossier separates documented institutional records from provider claims and interpretation. These are anchor records, not an exhaustive bibliography.